For many business owners, the roof is something you rarely think about, until there’s a leak, storm damage, or major repair bill. Your Commercial Property Insurance is designed to help protect your building, but many owners are surprised to learn that roof damage is one of the areas where coverage might be complicated.
Understanding roof exclusions and limitations in your Commercial Property policy can help you avoid unexpected expenses in the future. In today’s Aegis blog post, we take an in-depth look at roof damage and the factors that can impact your Commercial Insurance coverage.
Why Roof Coverage Can Be Complicated
Restaurants, cafés, hotels, retail stores, and other businesses rely on their buildings to operate without interruptions. But when you have roof issues, they can lead to water damage, lost inventory, ruined equipment, unsafe conditions for customers and employees, and even a temporary shutdown.
Commercial Property Insurance generally provides protection against many types of covered losses, including fire, wind, hail, and certain storm-related damage. But Business Insurance policies aren’t designed to cover every type of roof problem, and other policies like General Liability, aren't able to cover gaps in your existing Commercial Property coverage.
Depending on factors like age, maintenance, and other issues, your roof damage claim might not be as straightforward as a standard claim for a fire or theft of your property. The key is understanding what your policy covers and what might be excluded.
Maintenance-related Problems
Commercial Property Insurance generally isn't intended to pay for the normal aging, deterioration, or lack of maintenance of a roof. Insurance companies typically consider those issues part of the owner's responsibility.
Examples might include:
If it’s determined that the primary cause of the loss was wear and tear, deterioration, or inadequate maintenance, the cost of replacing the roof itself may be excluded.
Sudden Covered Events
Your roof claim can be very different when the roof is damaged by a sudden event that is covered by the policy.
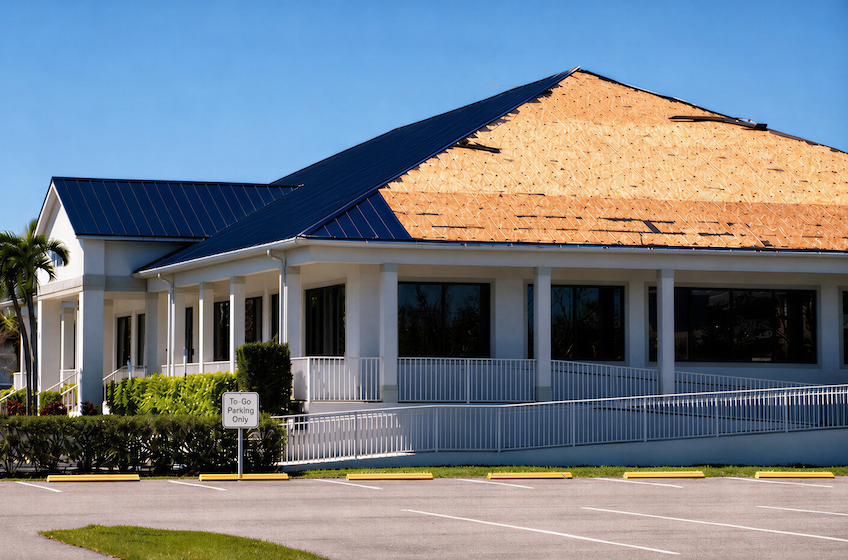
For example, if a severe windstorm tears a section of a commercial roof away or a hailstorm damages the roofing membrane, then those are potentially covered losses, assuming the policy covers those particular events and no exclusion or limitation applies.
In these situations, your insurance company will need to answers to questions such as:
The answers can significantly affect the amount of the claim payment and your ability to make a quick and full business recovery.
What If Storm Damage Impacts An Older Roof?
This is where things can get complicated. If your business has a 15-year-old roof with some existing deterioration and a major windstorm tears off a section of the roof, it could allow rain to enter the building.
The insurance company may distinguish between the pre-existing deterioration and the new storm damage. The storm damage may be covered while the underlying deterioration may not be.
In other words, insurance generally isn't intended to turn an old, worn-out roof into a brand-new roof simply because a covered event occurred. However, if a covered event causes legitimate damage to an otherwise serviceable roof, the resulting claim may be handled differently.
The exact outcome depends on the policy language, the facts of the loss, the condition of the roof, and applicable endorsements or limitations.
Why Documentation Matters
This is one reason regular roof maintenance and documentation are so important for business owners. Inspection reports, repair invoices, photographs, maintenance records, and documentation of previous storm damage can help establish the condition of the roof before a loss.
For a restaurant, retail store, hotel, or other commercial property, it's also important to understand whether your policy provides replacement cost or actual cash value for roof losses. Some policies or endorsements may impose special limitations based on roof age or condition.
The bottom line: A roof claim isn't necessarily determined simply by whether the roof is leaking. The cause of the damage matters. A sudden covered event may trigger coverage, while gradual deterioration or maintenance issues may be excluded.
Why Restaurants and Retail Businesses Should Pay Close Attention
A roof problem can quickly become more than just a building repair issue. For businesses with inventory, food products, equipment, and customers on-site, water damage can create significant operational problems.
A roof leak above a restaurant kitchen could damage electrical systems, ceiling materials, food storage areas, or expensive equipment. In a retail store, water intrusion could destroy merchandise and create slip-and-fall hazards for customers or your workers.
For hospitality businesses, even a short closure can result in lost revenue. This is why understanding both property coverage and business income protection is important.
Regular Roof Maintenance Can Protect Your Investment
Insurance is only one part of protecting your business. Preventative maintenance can help identify small problems before they become major losses.
Business owners should consider:
Maintaining your roof not only protects your property but can also demonstrate responsible ownership when filing a claim.
Review Your Policy Before You Need It
Many business owners don’t discover their roof coverage limitations until after a storm or major leak occurs. Taking time to review your Commercial Property policy before a loss happens can help you understand what is covered, what is excluded, and whether additional protection may be needed.
The experienced Commercial Insurance agents at Aegis can help you review key questions about your policy, including:
Your roof is a critical part of your business operation. Understanding your coverage and maintaining your property can help reduce surprises and keep your business running when unexpected problems occur.
Contact Aegis Insurance & Financial Services at 713-850-7622 for more information or to schedule a consultation with our Commercial Insurance agents.
Call Us TODAY!
713-850-7622